Businesses registered for sales tax occasionally encounter the 3rd Schedule of the Sales Tax Act, 1990 while calculating GST on goods – the details contained therein are relevant in helping businesses to calculate taxes accurately and remain compliant. This article provides an overview of the 3rd schedule of the sales tax Act and its implications for businesses registered for sales tax.
Understanding the 3rd Schedule
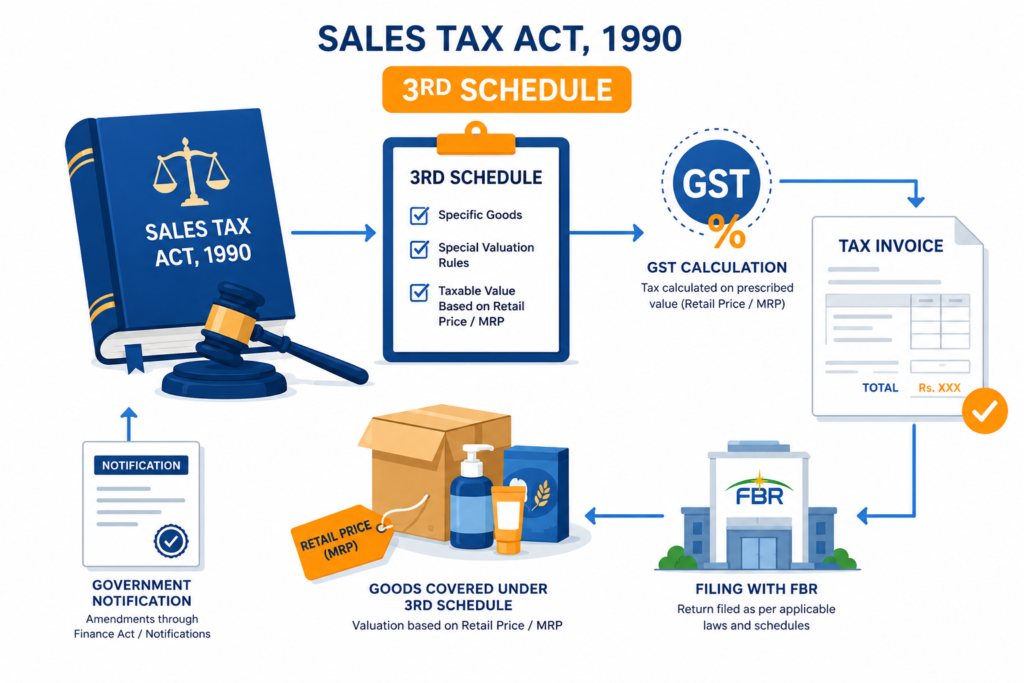
The Sales Tax Act 1990 3rd Schedule comprises of special provisions for a number of goods that have their taxable value calculated differently as compared to the usual transaction value. It contains a list of goods for which sales tax is computed on a retail price printed on the product or a maximum retail price (MRP), or other valuation criteria as may be prescribed by law. In recent years, a number of amendments to the Sales Tax Laws have been introduced, which can affect the applicability of the 3rd Schedule.
The following methods may be used for valuation of such goods:
- Retail price printed on the product
- Maximum retail price (MRP)
- Other valuation methods as prescribed by law
Why is the 3rd Schedule important?
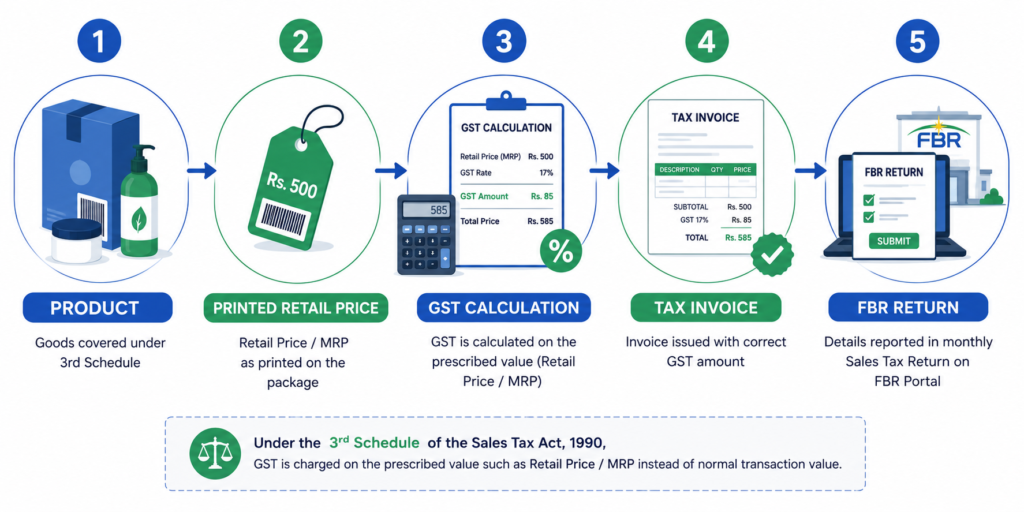
If your business involves manufacturing, import or supply of goods listed in the 3rd Schedule, your sales tax may deviate from the standard calculation method. This will impact the following:
- Sales tax invoicing
- GST calculations
- Pricing strategy
- Sales tax returns
- Compliance
The incorrect valuation method can result in misreporting of sales tax and consequently penalties in the event of an FBR audit. Sales tax compliance is only one of the pillars of a taxpayer’s compliance regime – businesses are also expected to file their annual income tax returns correctly, in order to avoid additional penalties and remain compliant with income tax laws.
Goods Most Frequently Taxed under the 3rd Schedule
While the list of goods covered under the 3rd Schedule may be modified from time to time, goods that were frequently covered under the 3rd Schedule comprised of consumer products with a regulated retail price. Such goods include:
- Cosmetics
- Beverages
- Toiletries
- Packaged goods
- Other notified goods
It is critical for businesses to refer to the latest version of the Schedule in order to ascertain whether their goods are subject to special valuation provisions.
Guidelines for Businesses
Here are some of the practical steps businesses can take in order to deal with the 3rd Schedule:
- Ascertain whether a particular product falls under the 3rd Schedule
- Identify the prescribed valuation method
- Calculate sales tax under the identified taxable value
- Invoice as per calculated GST amount
- Report accurately in monthly sales tax returns
When there is ambiguity around the classification of goods, it is always recommended to get professional tax advice in order to avoid reporting errors.
Common Mistakes to Avoid
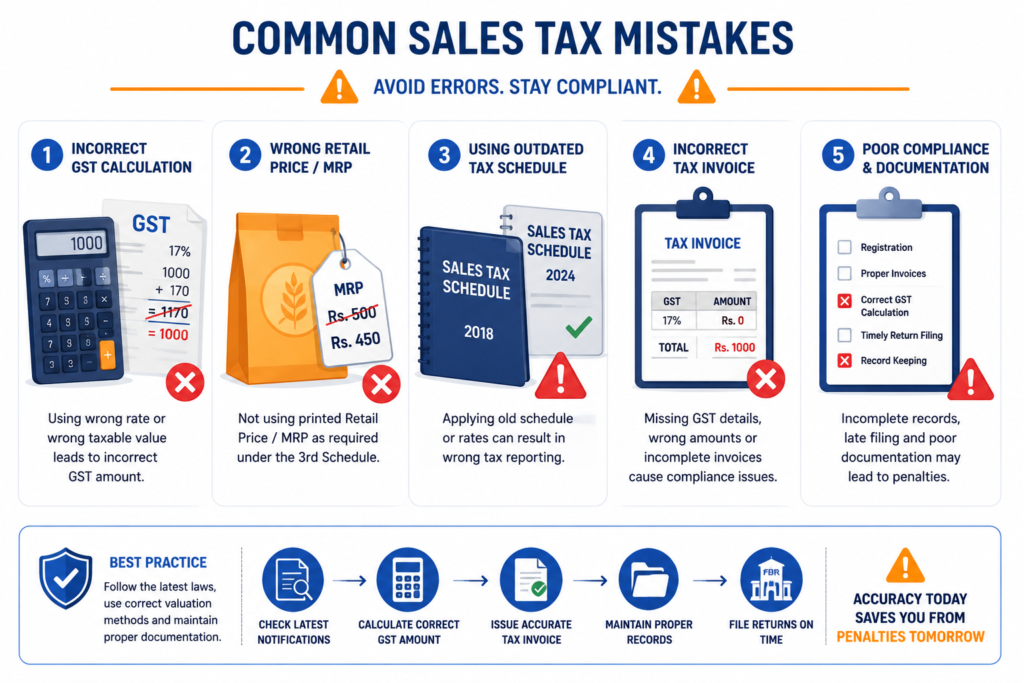
- Assuming that valuation is based on the transaction value
- Failure to consider updates issued by way of Finance Acts
- Incorrect GST calculation based on wrong taxable value
- Inaccurate classification of goods
- Sales tax return filing without considering valuation methods
There are a number of common errors that businesses tend to make due to lack of detailed understanding of the 3rd Schedule. Small valuations errors in sales tax calculations can balloon into significant compliance issues in the wake of an FBR audit.
Frequently Asked Questions
What is the 3rd Schedule of Sales Tax?
The 3rd Schedule of the Sales Tax Act, 1990 prescribes special provisions in respect of certain goods in Pakistan. Instead of being subjected to the normal computation of sales tax based on the transaction value, the taxable value of a certain set of goods is determined by the printed retail price (MRP) or other valuation methods as prescribed under the law. The 3rd Schedule aims to ensure consistency in sales tax collection on selected consumer products.
Does every business need to adhere to the 3rd Schedule?
No. The 3rd schedule of sales tax only applies to businesses that manufacture, import, distribute or sell goods notified under the 3rd Schedule. If your products are not included in the Schedule, you would apply the standard valuation rules provided under the Sales Tax Act, 1990. Businesses should always confirm whether their products are included in the 3rd Schedule.
Does the 3rd Schedule change?
Yes. It is possible for the government to make additions, deletions or modifications to the 3rd Schedule through the Finance Acts, SROs or other notifications issued by the FBR. Business taxpayers should review the latest amendments issued by the FBR and comply accordingly.
How do I know if my products are included?
You can refer to the latest Sales Tax Act, 1990 – 3rd schedule of sales tax to ascertain whether your goods are covered under the Schedule. It is also important to correctly classify goods in order to identify the applicable valuation rules under the Sales Tax Act. In the event of an uncertainty around the classification of goods, it is best to get professional tax advice to avoid inadvertent errors in sales tax reporting.
Can using a wrong valuation method result in penalties?
Yes. Incorrect valuation method can result in errors in sales tax calculation, GST and sales tax returns. In the event of an FBR audit, such errors can be penalized and additional tax may be levied depending on the severity of the errors and the auditor’s discretion. Verifying valuation rules before issuing invoices and filing sales tax returns can help you avoid such penalties.
FAQs
Does the 3rd Schedule apply to services or only goods?
The 3rd Schedule only applies to goods – services are governed by separate provincial sales tax laws.
How do I know whether my product falls under the 3rd Schedule?
Check the applicability of the 3rd Schedule based on the category of goods in question – it only applies to select goods (such as certain packaged goods and cosmetics) and not all goods in general.
What happens if I charge sales tax incorrectly based on the 3rd Schedule?
Under-charging sales tax incurs a shortfall that you will have to make up for whereas over-charging sales tax might lead to customer complaints – getting the basis for sales tax computation correct on your invoices is more important in such situations as compared to regular invoice-based sales tax calculations.