A 182(2) notice means FBR believes you didn’t file a required return and is proposing a penalty for it — here’s what it actually means and how to respond.
What Triggers a 182(2) Notice
Under Section 114 of the Income Tax Ordinance, certain people are required to file an income tax return — and if FBR’s records show no return was filed (and no extension/adjournment was granted) by the due date, they can issue a notice under Section 182(1) proposing a penalty for the failure to furnish a return under Section 114.
Common Reasons People Get This Notice Even When They Think They Filed
- A previous year’s return wasn’t actually filed — sometimes the notice relates to an older tax year, not the most recent one, and gets overlooked.
- A return was started but never submitted — a draft return in IRIS that was never finally submitted doesn’t count as filed.
- Filing was done under the wrong CNIC/NTN — a data-entry mismatch can make FBR’s system show no return against your actual registered number.
- You were newly required to file — a change in your income or asset profile can trigger a filing requirement you weren’t previously subject to, without you realizing it.
What to Do When You Receive This Notice
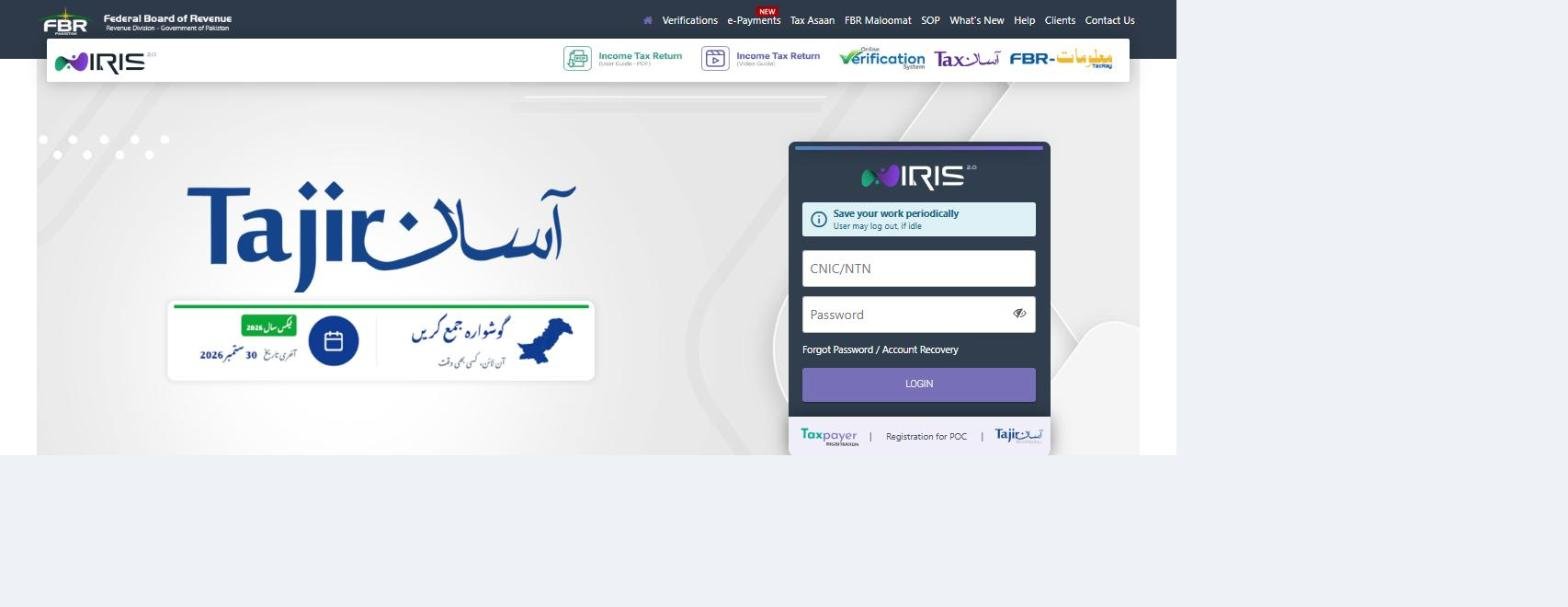
- Verify whether you actually filed — log into IRIS and check your filing history for the specific tax year the notice references.
- If you genuinely didn’t file, file immediately — filing a late return, even after the notice, is almost always better than ignoring it; it demonstrates compliance and can affect how the penalty is ultimately assessed.
- If you did file but the notice says otherwise, respond with evidence — submit your filing confirmation/acknowledgment as a reply to the notice within the response window given.
- Don’t ignore the deadline in the notice — a non-response within the given timeframe can result in the penalty being finalized without further opportunity to explain.
What the Penalty Actually Is
Section 182(1) Sr. No. 1 sets out the penalty structure for failure to file a required return — the exact amount depends on your case specifics (a statutory minimum applies, with the penalty otherwise often calculated relative to tax payable or a per-day rate up to a cap). Always check the current Section 182 penalty table rather than assuming a fixed figure, since amounts get revised by Finance Act changes.
How to Avoid This Notice Going Forward
File your return on time every year, even if you believe you owe zero tax — a nil return still satisfies your Section 114 obligation and prevents exactly this kind of notice. See our guide on checking your filer status to confirm you’re current before a notice like this arrives.
Frequently Asked Questions
No schema found.
No schema found.