Reporting Other Sources Income in the New IRIS Return
Not all forms of income can be classified as Employment, Property, Business or Capital Gains. Dividends, profit on debt, royalties, prizes, winnings, annuities or any other income that cannot be classified as Employment, Property, Business or Capital Gains will fall under Other Sources. Select Other Sources as an income source on the Return Prerequisites screen if you have this type of income.
For a complete step-by-step of the entire income return from login to submission, refer to our step-by-step guide to filing your income tax return online.
Step 1: Other Income
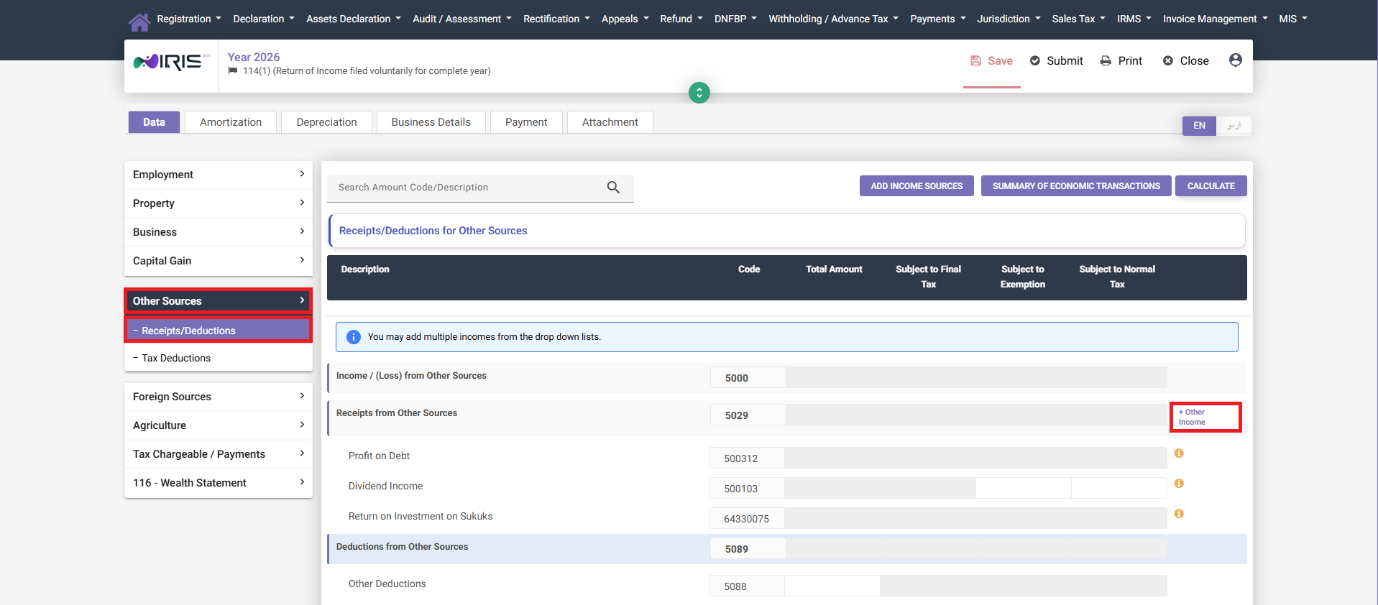
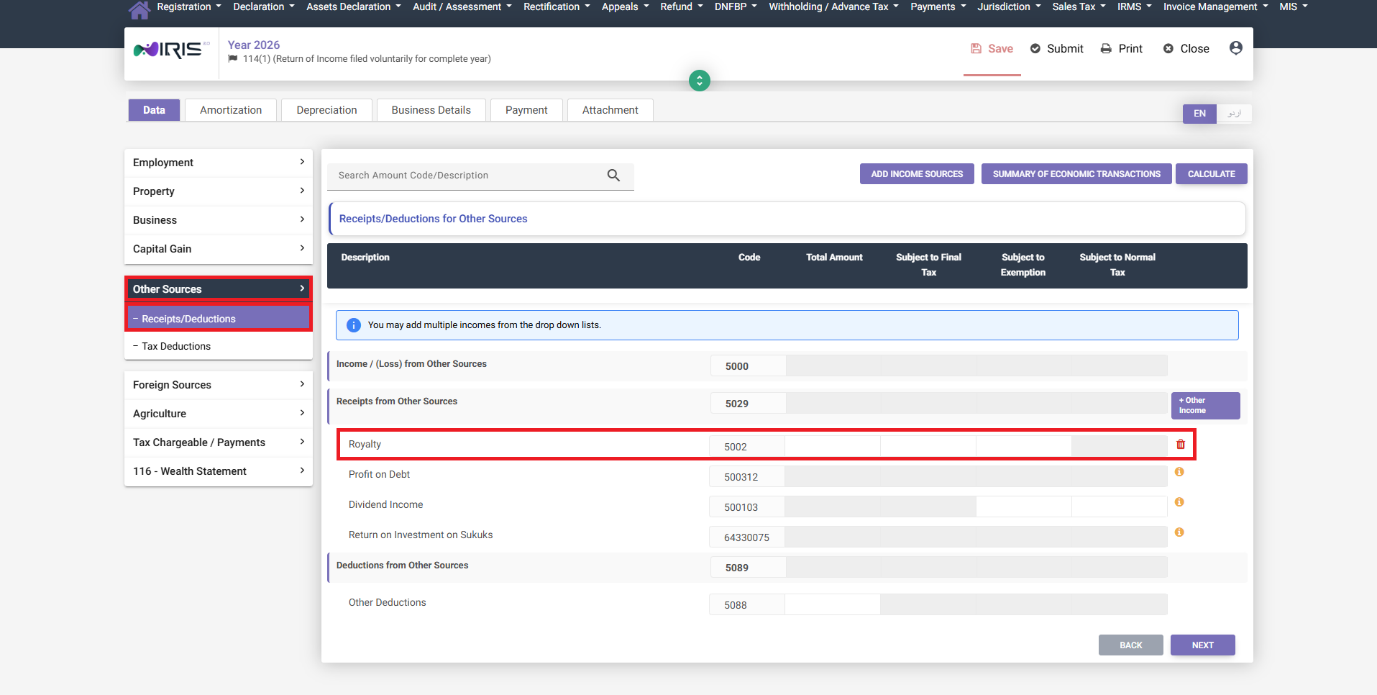
Navigate to Other Sources and select Receipts/Deductions. Click + Other Income and select the relevant source/s of income from the dropdown list and click Add – this will populate the grid.
There are a few categories that are auto-populated / locked i.e. Profit on Debt, Dividend Income, Return on Investment on Sukuks. Should the figures for these need amending, the Tax Deduction tab should be navigated to and the relevant sections added here as these are the figures which feed through to auto-populate these figures.
For any Other Income sources that can be manually inputted, enter the relevant figures and click Calculate and Next.
Step 2: Tax Deductions
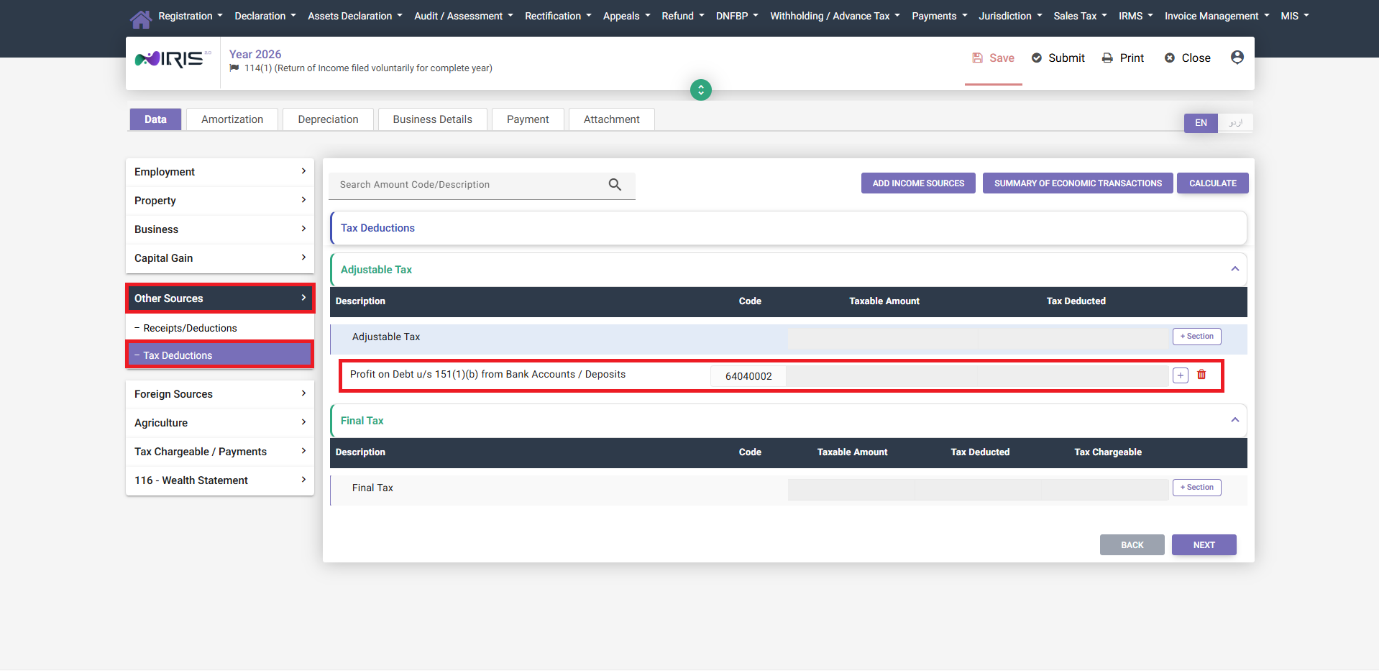
Under Tax Deductions, normally both Adjustable Tax and Final Tax entries will need to be added depending on the nature of the Other Sources income:
- Click + Section under Adjustable Tax and select the relevant category and click Add.
- Click + Section under Final Tax and select the relevant category and click Add.
- Add the relevant figures against each entry and click Calculate and Next.
Common Errors Seen With Other Sources Income
- Manually attempting to edit Profit on Debt or Dividend Income in the Receipts/Deductions tab. These fields are not editable and should only be amended on the Tax Deduction tab.
- Not declaring prize or winning income as this is often considered a one-off and does not need to be reported – however it is classed as Other Sources income and should be declared as such.
- Not declaring both Adjustable and Final Tax entries where the nature of the Other Sources income is such that both apply.
FAQ
What is classed as Other Sources income?
Dividends, profit on debt, royalties, prizes, winnings, annuities or any other taxable income that cannot be classified as Employment, Property, Business or Capital Gains.
Why can’t I edit my dividend income?
Dividend income, profit on debt, Sukuk returns are auto-populated and locked. To edit the amount a section should be added on the Tax Deduction tab to reflect this.
Is prize money or winning from a raffle/competition taxable?
Yes – this should be reported as Other Sources income. This is likely to be subject to tax at source so a corresponding Final Tax entry should be added on the Tax Deductions tab.